Chapter 01
The first months
Securing the property, the notices California requires and the values that set the tax basis for heirs.
The first weeks: securing the trust property
Before anything is sold or distributed, the trustee takes control and documents what the trust owns:
- Locate the original trust, every amendment and the pour-over will.
- Order certified copies of the death certificate.
- Secure the home, vehicles and valuables, and keep insurance in force.
- Obtain an employer identification number (EIN) for the now-irrevocable trust.
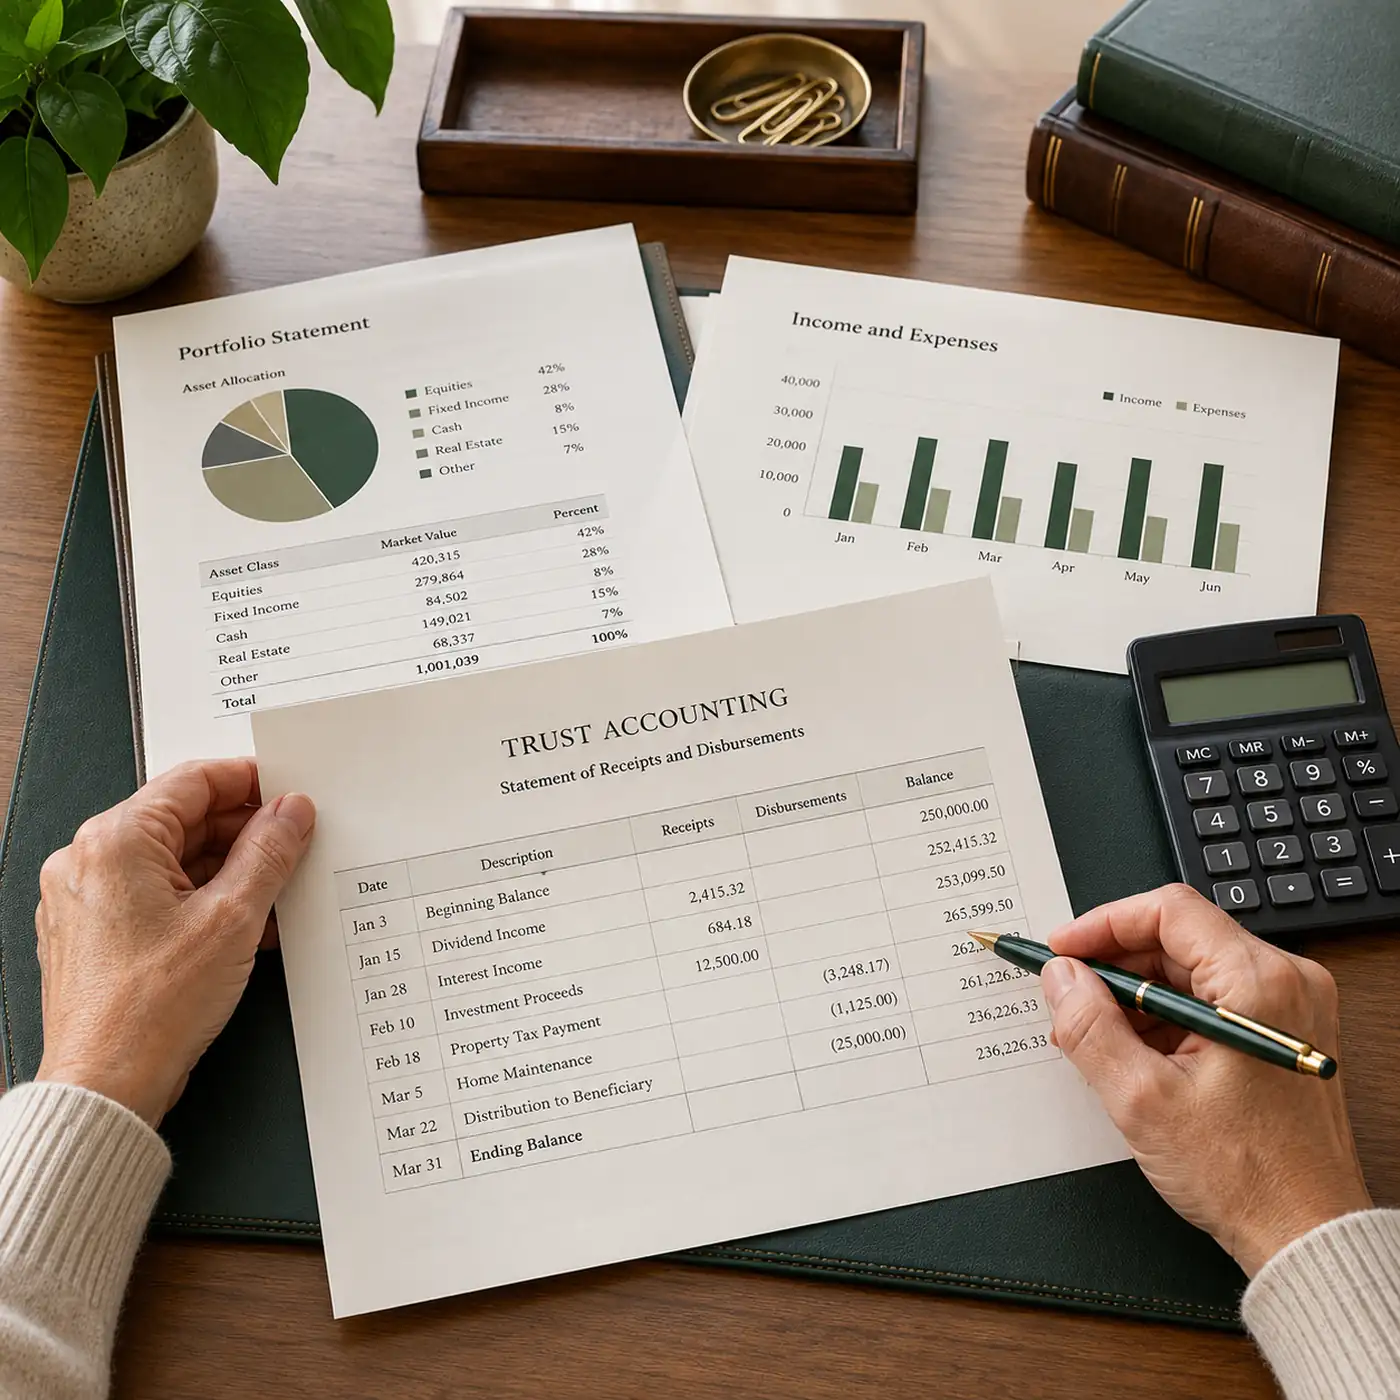
- Open a trust account so income and expenses are never mixed with personal funds.
- Gather statements, deeds and recent tax returns, and list any assets left outside the trust.
Notice to beneficiaries and heirs
California requires the trustee to serve a notification on every beneficiary and on the decedent’s heirs within 60 days after the trust becomes irrevocable (Probate Code §16061.7). The notice must contain specific information, including the trustee’s name and address and a statement that the recipient may request a copy of the trust terms. A beneficiary or heir who wants to contest the trust generally must do so within 120 days after the notice is served, or 60 days after a requested copy of the trust is delivered, whichever is later (§16061.8). Serving the notice correctly starts that clock.
Valuing assets and the step-up in basis
The trustee obtains date-of-death values for real estate, securities and business interests. Those values set the new income tax basis for inherited property (Internal Revenue Code §1014), which can eliminate capital gains tax on appreciation during the decedent’s lifetime. For a married couple’s community property, both halves generally receive a new basis at the first death (§1014(b)(6)). Appraisals also support the property tax filings, the estate tax analysis and a fair division among beneficiaries.