Personal estate planning counsel in Northern California
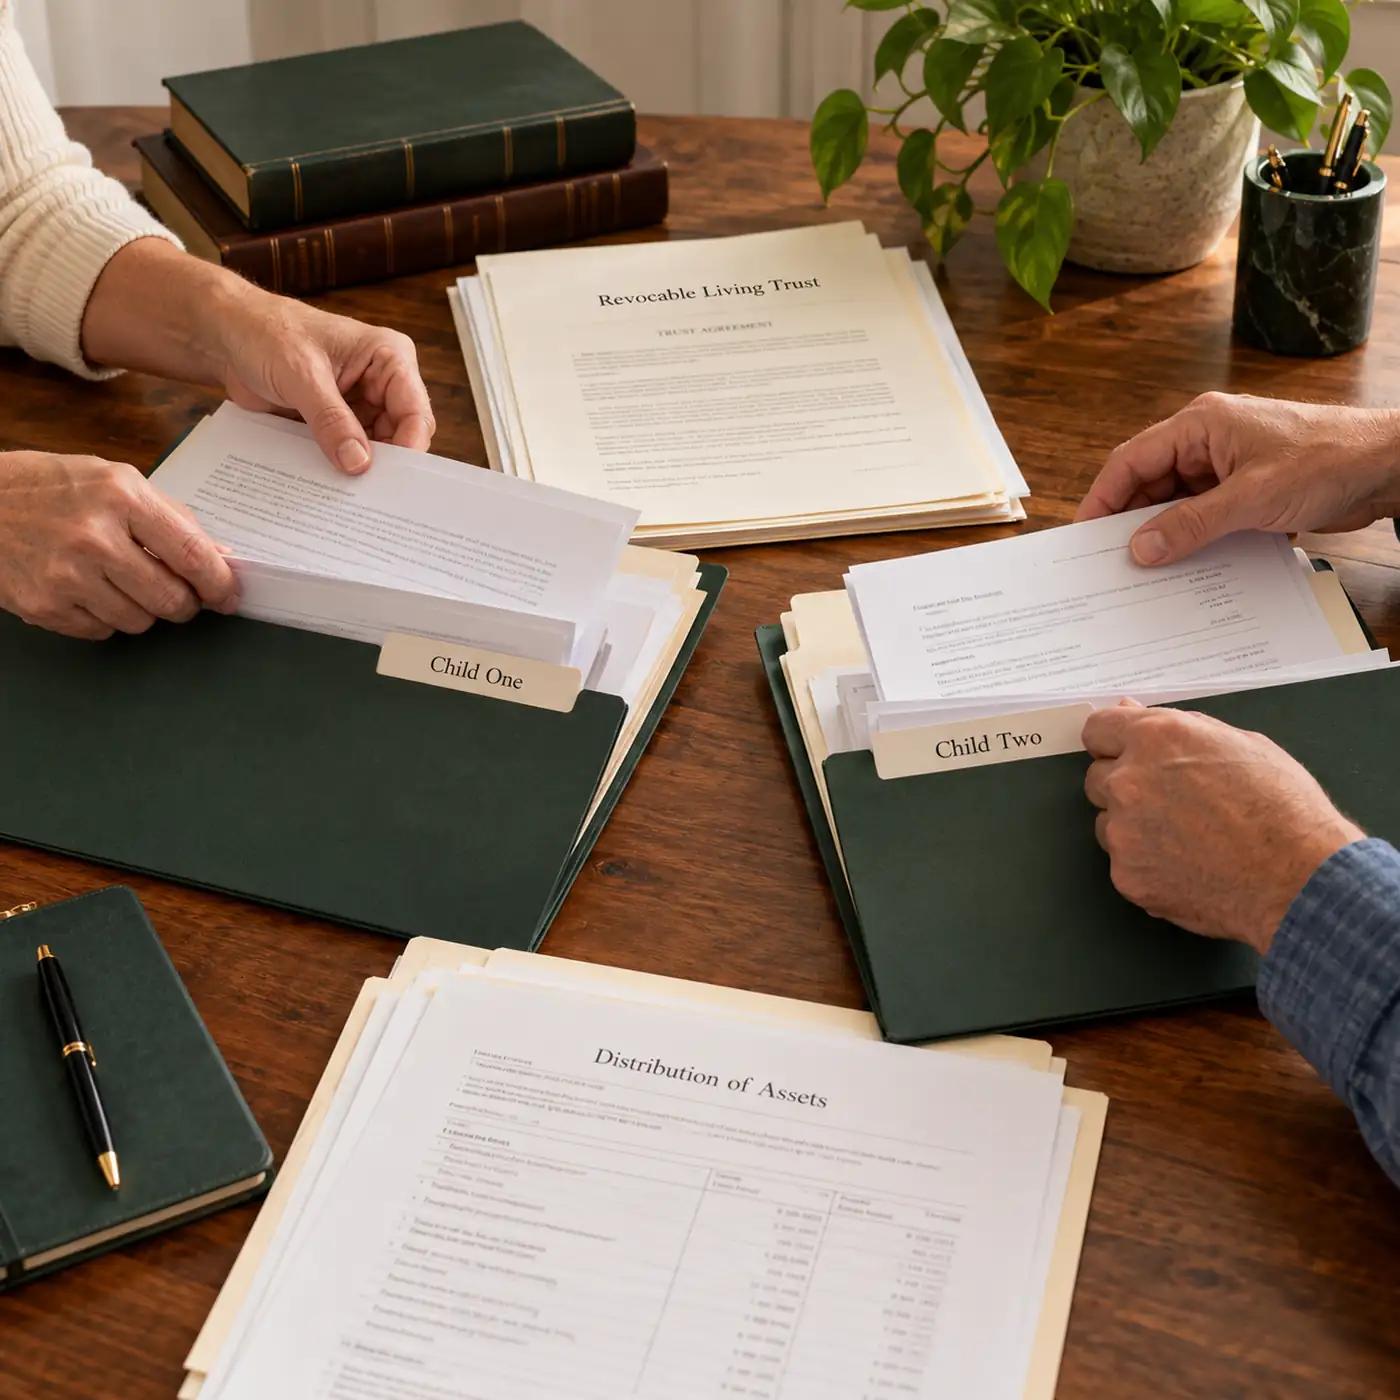
Family papers sorted into folders at a dining table

Practice area · Trust Administration

Trust Administration in California

Step-by-step guidance for successor trustees — the notices, deadlines, taxes and accountings California requires before a trust can be distributed.

Counsel
Elaine Andrews, Certified Specialist
Service area
Northern California · Office in Truckee
First meeting
Free initial consultation

In plain terms

Trust administration is the work a successor trustee does after a trust becomes irrevocable, usually at the death of the person who created it: securing and valuing the trust property, notifying beneficiaries and heirs, paying valid debts, expenses and taxes, keeping beneficiaries informed and distributing what remains under the trust’s terms. In California most trust administrations take place without court supervision, but the trustee is a fiduciary bound by the duties in Probate Code §16000 and following.

A trustee’s job in plain terms

Being named successor trustee is an honor and a legal responsibility. The trustee must follow the trust document, act in the beneficiaries’ interest rather than their own, treat beneficiaries impartially, invest prudently and keep accurate records. Mistakes — a missed deadline, a sale at the wrong price, a distribution before taxes are paid — can make the trustee personally liable. The Andrews Law Firm, P.C. guides trustees through each stage, and Elaine Andrews is also a California credentialed professional fiduciary.

  1. 01 The first months The first weeks: securing the trust property · Notice to beneficiaries and heirs · Valuing assets and the step-up in basis
  2. 02 Money and taxes Property tax and real estate · Debts, expenses and creditor claims · Income tax and estate tax returns
  3. 03 Accountability Keeping beneficiaries informed and accounting · Trustee compensation and getting help · When the court becomes involved
Two adult siblings sorting family papers at a dining table

Chapter 01

The first months

Securing the property, the notices California requires and the values that set the tax basis for heirs.

The first weeks: securing the trust property

Before anything is sold or distributed, the trustee takes control and documents what the trust owns:

  • Locate the original trust, every amendment and the pour-over will.
  • Order certified copies of the death certificate.
  • Secure the home, vehicles and valuables, and keep insurance in force.
  • Obtain an employer identification number (EIN) for the now-irrevocable trust.
  • Open a trust account so income and expenses are never mixed with personal funds.
  • Gather statements, deeds and recent tax returns, and list any assets left outside the trust.

Notice to beneficiaries and heirs

California requires the trustee to serve a notification on every beneficiary and on the decedent’s heirs within 60 days after the trust becomes irrevocable (Probate Code §16061.7). The notice must contain specific information, including the trustee’s name and address and a statement that the recipient may request a copy of the trust terms. A beneficiary or heir who wants to contest the trust generally must do so within 120 days after the notice is served, or 60 days after a requested copy of the trust is delivered, whichever is later (§16061.8). Serving the notice correctly starts that clock.

Valuing assets and the step-up in basis

The trustee obtains date-of-death values for real estate, securities and business interests. Those values set the new income tax basis for inherited property (Internal Revenue Code §1014), which can eliminate capital gains tax on appreciation during the decedent’s lifetime. For a married couple’s community property, both halves generally receive a new basis at the first death (§1014(b)(6)). Appraisals also support the property tax filings, the estate tax analysis and a fair division among beneficiaries.
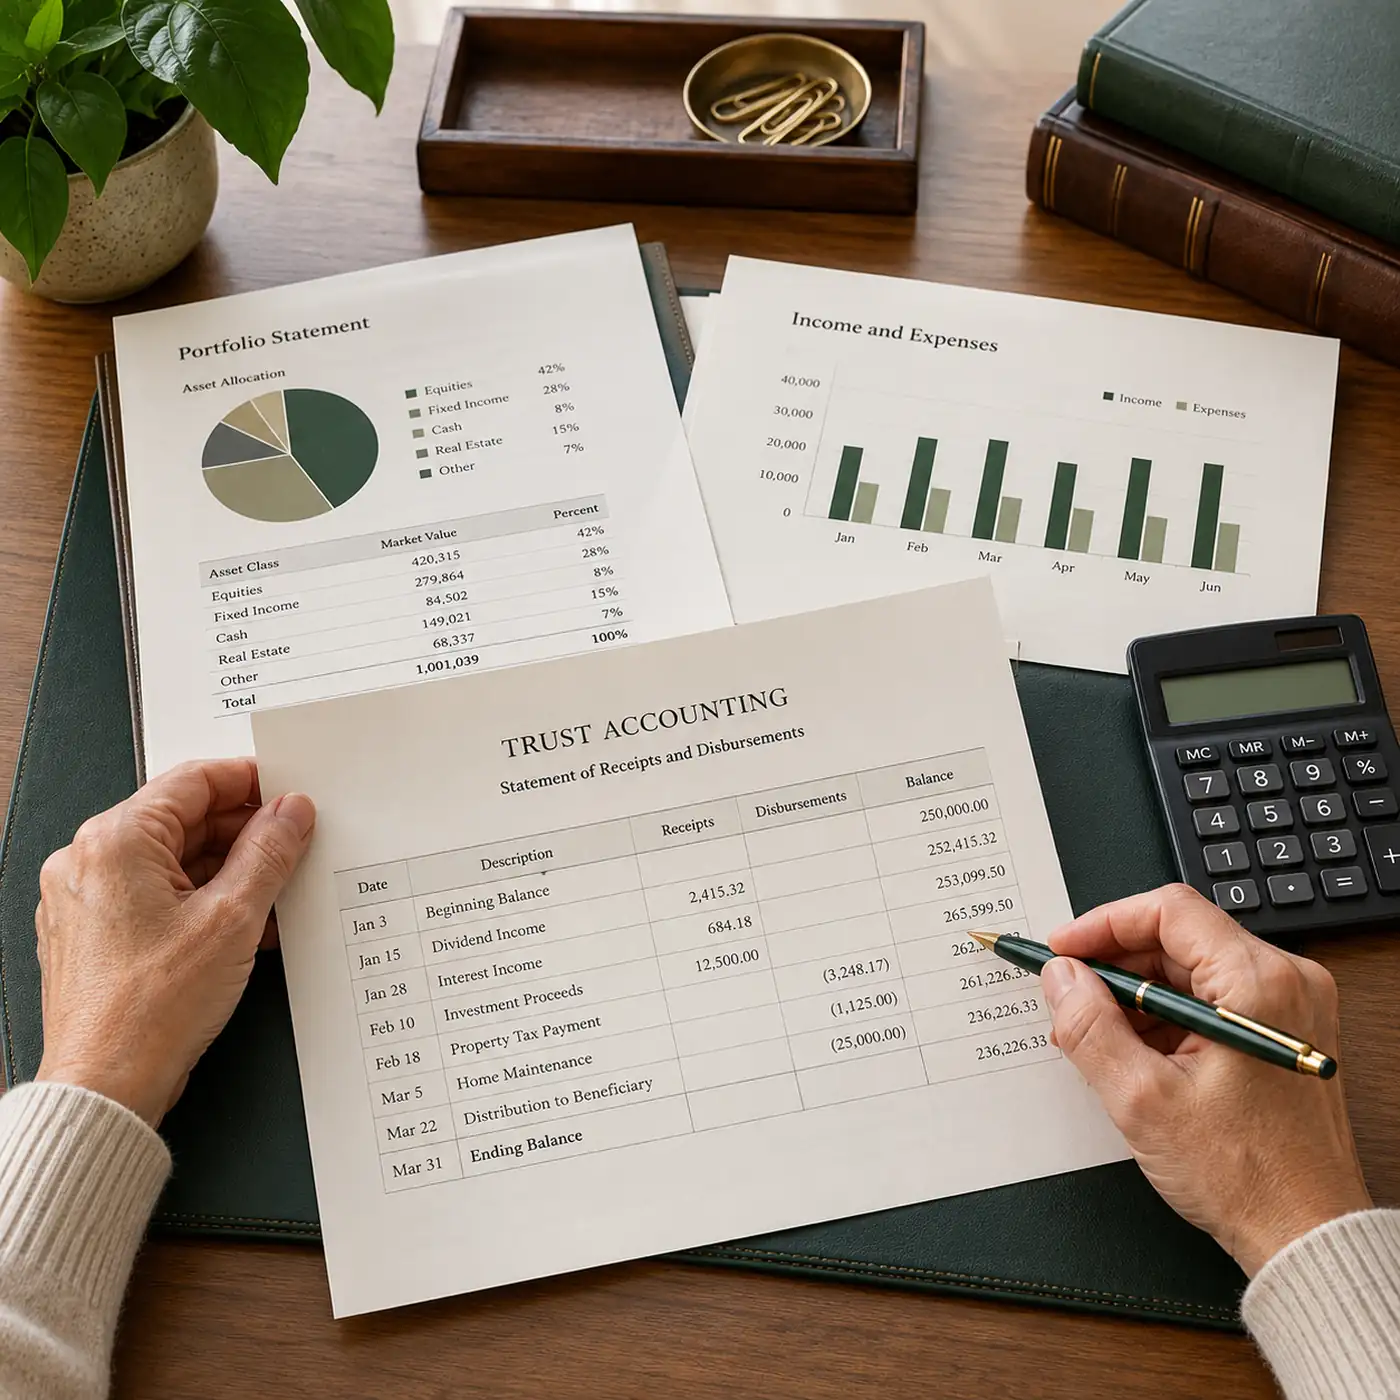
A calculator, reading glasses and statements on a desk by a window

Chapter 02

Money and taxes

Property tax filings, debts and creditor claims, and the income and estate tax returns a trustee coordinates.

Property tax and real estate

A change in ownership statement (form BOE-502-D) is due to the county assessor within 150 days after the date of death (Revenue and Taxation Code §480). Real property passing to children qualifies for the Proposition 19 parent-child exclusion only if it is a family home that becomes the child’s principal residence or a family farm, and only up to the parent’s taxable value plus $1,044,586 for transfers between February 16, 2025 and February 15, 2027; the claim must be filed with the assessor. A home that will be sold is maintained, insured and listed by the trustee, and the sale is documented for the accounting.

Debts, expenses and creditor claims

The trustee pays valid debts, final expenses and the costs of administration from trust assets before distributing. California offers an optional procedure for trust creditor claims (Probate Code §19000 and following) in which notice is published and given to known creditors, cutting off late claims. Whether to use it depends on the decedent’s debts and the risk of unknown claims. Beneficiaries should not receive distributions until the trustee is confident enough remains for taxes and claims.

Income tax and estate tax returns

The trustee arranges the decedent’s final personal income tax returns and, during the administration, the trust’s own returns (federal Form 1041 and California Form 541) when the trust has income. A federal estate tax return (Form 706) is due nine months after death if the gross estate exceeds the exemption — $15 million per person in 2026 — and is often filed for a married decedent even when no tax is due, to elect portability of the unused exemption for the surviving spouse. California has no estate or inheritance tax.

A signed document and a fountain pen on a wooden table

Chapter 03

Accountability

Keeping beneficiaries informed, trustee compensation and the situations that call for a court petition.

Keeping beneficiaries informed and accounting

A trustee must keep beneficiaries reasonably informed and respond to their reasonable requests for information (Probate Code §16060–16061), and must account to beneficiaries at least annually, when the trust terminates and when the trustee changes, unless an exception applies (§16062). A clear accounting lists what the trust held at the start, every receipt and disbursement, gains and losses, and what remains. Beneficiaries who approve the accounting and sign a receipt and release give the trustee closure.

Trustee compensation and getting help

A trustee is entitled to the compensation the trust provides or, if the trust is silent, reasonable compensation under the circumstances (Probate Code §15681), and may hire attorneys, accountants and appraisers at the trust’s expense. A trustee who cannot or does not want to serve can decline or resign under the trust’s terms. Family members who serve as trustee often handle day-to-day tasks while the attorney handles the notices, the legal questions and the documentation.

When the court becomes involved

Most trust administrations never go to court. A petition may be needed to confirm that an asset left outside the trust belongs to it (a Heggstad petition, Probate Code §850), to interpret an unclear provision, to approve an accounting, to resolve a dispute among beneficiaries or to remove a trustee (§17200, §15642). Trust proceedings are generally filed in the superior court of the county where the trust is principally administered (§17005).

A brother and sister reviewing papers together at a dining table

Who this is for

Talk with a trust administration attorney if any of these is true.

Talk it through
  • You were named successor trustee of a parent’s or relative’s trust.
  • You are serving as trustee after your spouse’s death.
  • You are a beneficiary waiting for a trust to be settled.
  • You are co-trustee with a sibling and unsure who does what.
  • The trust holds a home, cabin or rental that now has to be sold or divided.
  • An asset was never transferred into the trust.
  • Other beneficiaries have questions or disagree with decisions.

How it works

From the first notice to the final distribution.

Direct guidance from a Certified Specialist at every step.

  1. 01

    First meeting

    Review the trust, the assets and the family situation, and set a timeline.

  2. 02

    Notices

    Prepare and serve the Probate Code §16061.7 notification on beneficiaries and heirs.

  3. 03

    Inventory and values

    Gather statements and obtain appraisals and date-of-death values.

  4. 04

    Bills and taxes

    Pay valid debts and expenses, file the change in ownership statement and coordinate tax returns.

  5. 05

    Accounting

    Prepare an accounting for the beneficiaries’ review.

  6. 06

    Distribution

    Transfer assets, record deeds and obtain signed receipts.

California at a glance

Trust Administration, by the numbers that matter.

Notice deadline
60 daysAfter a trust becomes irrevocable, the trustee serves notice on beneficiaries and heirs within 60 days (Probate Code §16061.7).
Contest window
120 daysFrom service of that notice, or 60 days after a requested copy of the trust is delivered, whichever is later (Probate Code §16061.8).
Accountings
At least annuallyTrustees generally account to current beneficiaries yearly, at termination and on a change of trustee (Probate Code §16062).
Core duties
Loyalty, impartiality, prudenceTrustees must administer solely for beneficiaries, keep them reasonably informed and invest prudently (Probate Code §16000–16061).

General California and federal information current as of 2026. Figures adjust over time and every situation is different; confirm how a rule applies to you before acting.

Mistakes we see most often.

Distributing before taxes and debts are settled
A trustee who empties the trust too early can be personally liable for unpaid taxes or claims.
Skipping the 60-day notice
Without a proper §16061.7 notice, the period to contest the trust never starts to run.
Mixing trust money with personal accounts
Commingling makes the accounting difficult and can be a breach of the trustee’s duties.
Letting one beneficiary live in the house rent-free
Unless the trust allows it, this can be unfair to the others and lead to disputes.
Missing the property tax filings
A late change in ownership statement or Proposition 19 claim can cost penalties or the exclusion.
Selling to a family member without documenting value
Sales to a beneficiary or relative need appraisals, disclosure and clear records.

This page covers

  • Successor trustee duties
  • Probate Code §16061.7 notice
  • 120-day contest period
  • Date-of-death values
  • Step-up in basis
  • Change in ownership statement
  • Proposition 19
  • Trust creditor claims
  • Form 1041 and Form 541
  • Portability elections
  • Trust accountings
  • Heggstad petitions

In clients’ own words.

All client reviews
Posted on Google Google
Ronald Schmader profile picture
Ronald Schmader
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
As grieving parents of our deceased son, we were in need of guidance with regard to what do we do next. Our son was without a will and, we had no experience with how to proceed. Luckily, we contacted Elane at the Andrews Law Firm Truckee who immediately understood our situation and was able to provide the information we needed and the necessary legal paperwork to resolve our problem. Our problem was magnified by the fact that we live in Milwaukee and involved my son's car for which we could not find the title. Rather than have to return to Truckee after 40 days to request a new title, Elane assisted us in creating a power attorney for a friend in Truckee which negated our having to return to Truckee from Milwaukee to simply apply for a new title. We are very appreciative with the help we found at The Andres Law Firm Truckee. Thank you, Elaine!
Posted on Google Google
David VanderJagt profile picture
David VanderJagt
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We really appreciate all the excellent work the Andrew’s Law Firm has done with updating our Trust. Her attention to detail is very appreciated and guiding us through our Trust planning has been exemplary . David and Linda VanderJagt
Posted on Google Google
I “Sue” S profile picture
I “Sue” S
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Quick and efficient handling of my new Trust.
Posted on Google Google
Stephanie (Lady Lebala) profile picture
Stephanie (Lady Lebala)
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We were referred to Elaine Andrew's law firm through a friend and I'm very happy we went and sat down with her. She quickly recognized a few mistakes in our previous trust and worked to correct them and ensure that our trust followed all legal requirements. We now feel confident that we have a very solid trust for the future.
Posted on Google Google
Cindy Ann Homer profile picture
Cindy Ann Homer
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Elaine was very supportive and professional. She sincerely listened to my concerns and questions. She advised me of California Laws and guided me through the process of what steps would be the best for preparing my will. Kenneth reviewed page by page of my will with me (before signing) and answered all of my questions. I highly recommend The Andrews Law Firm they made my dreaded will preparation bearable. Thank you.
Posted on Google Google
Linda Smith profile picture
Linda Smith
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Process was quick and easy. Appreciated all the help they provided.

This testimonial or endorsement does not constitute a guarantee, warranty, or prediction regarding the outcome of your legal matter.

Frequently asked questions

Questions clients ask about trust administration.

Straight answers to start with. Bring your own documents and circumstances to a free consultation for advice that fits.

All frequently asked questions
Do I need court approval to administer a trust in California?

Usually not. Most trust administrations proceed without court supervision. The court becomes involved when there is a dispute, an unclear provision, a request to approve an accounting or an asset that was never transferred to the trust.

How long does trust administration take?

It depends on the assets, taxes and beneficiaries. The 120-day contest period, the time needed to sell or transfer real estate and any estate tax return often set the pace; many administrations take from several months to more than a year.

What notice do I have to send, and when?

A notification to every beneficiary and heir within 60 days after the trust becomes irrevocable, with the information Probate Code §16061.7 requires. A new notice is also required when the trustee changes.

Can a beneficiary contest the trust?

Yes, generally within 120 days after the notice is served or 60 days after a requested copy of the trust is delivered, whichever is later (Probate Code §16061.8). After that, most contests are barred.

Do I have to give the beneficiaries an accounting?

Generally yes — at least annually, at termination and when the trustee changes (Probate Code §16062) — unless the trust or a beneficiary’s written waiver provides otherwise, within the limits of the law.

Can I be paid for serving as trustee?

Yes. You are entitled to the compensation the trust provides or, if it is silent, reasonable compensation (Probate Code §15681). Compensation is taxable income to the trustee.

Am I personally liable as trustee?

A trustee who follows the trust, the Probate Code and sound advice is generally protected. Liability arises from breaches such as self-dealing, commingling, imprudent investment or distributing before paying taxes and debts.

What if a home in the trust still has a mortgage?

Keep making the payments. Federal law generally prevents a lender from calling a residential loan because the home passes to a relative after the borrower’s death. The trustee decides with the beneficiaries whether to sell, refinance or distribute the home.

What happens to assets that were never put in the trust?

The pour-over will directs them to the trust, but they may require probate if they exceed $208,850. A small-estate procedure or a Heggstad petition (Probate Code §850) may avoid a full probate.

Does the trust need to file tax returns?

If the trust earns income during the administration, it files federal Form 1041 and California Form 541 under its own employer identification number. The decedent’s final personal returns are filed separately.

Should the trustee sell the house or distribute it?

It depends on the beneficiaries’ wishes, the trust’s terms, Proposition 19, the new tax basis and the carrying costs. Selling soon after death often produces little or no capital gain because of the step-up in basis.

Can I resign as trustee?

Yes. A trustee can resign as the trust provides, with the consent of the beneficiaries or with court approval, and the next named successor takes over.

Northern California service areas

Local guidance, without the long list.

Explore the regions where The Andrews Law Firm provides California-focused counsel. Find your community from one organized coverage page, or contact our Truckee office for consultation options.

View areas served

Related practice areas

Start with one clear conversation.

Bring your questions, your documents and the decisions you want help with. The first consultation is free.