Chapter 01
The agreement
The events a succession plan must answer, how buy-sell agreements work and how the price is set.
The five events a plan must answer
A buy-sell agreement should address each triggering event:
- Death — who buys the interest from the owner’s estate, at what price and with what money.
- Disability — when incapacity triggers a buy-out and who manages until then.
- Retirement — whether an owner can sell back the interest and over what period.
- Departure — what happens when an owner quits, is removed or competes.
- Divorce — in California a spouse may hold a community property interest; the agreement can give the company or the other owners a right to buy it.
Buy-sell agreements: cross-purchase or redemption
In a cross-purchase agreement, the remaining owners buy the departing owner’s interest, often funded by life insurance each owner holds on the others. In an entity redemption, the company buys the interest back. In Connelly v. United States (2024), the U.S. Supreme Court held that life insurance proceeds a corporation receives to redeem a deceased owner’s shares increase the company’s value for estate tax purposes, with no offset for the redemption obligation — so many owners are reviewing redemption agreements funded with company-owned insurance.
Setting the price
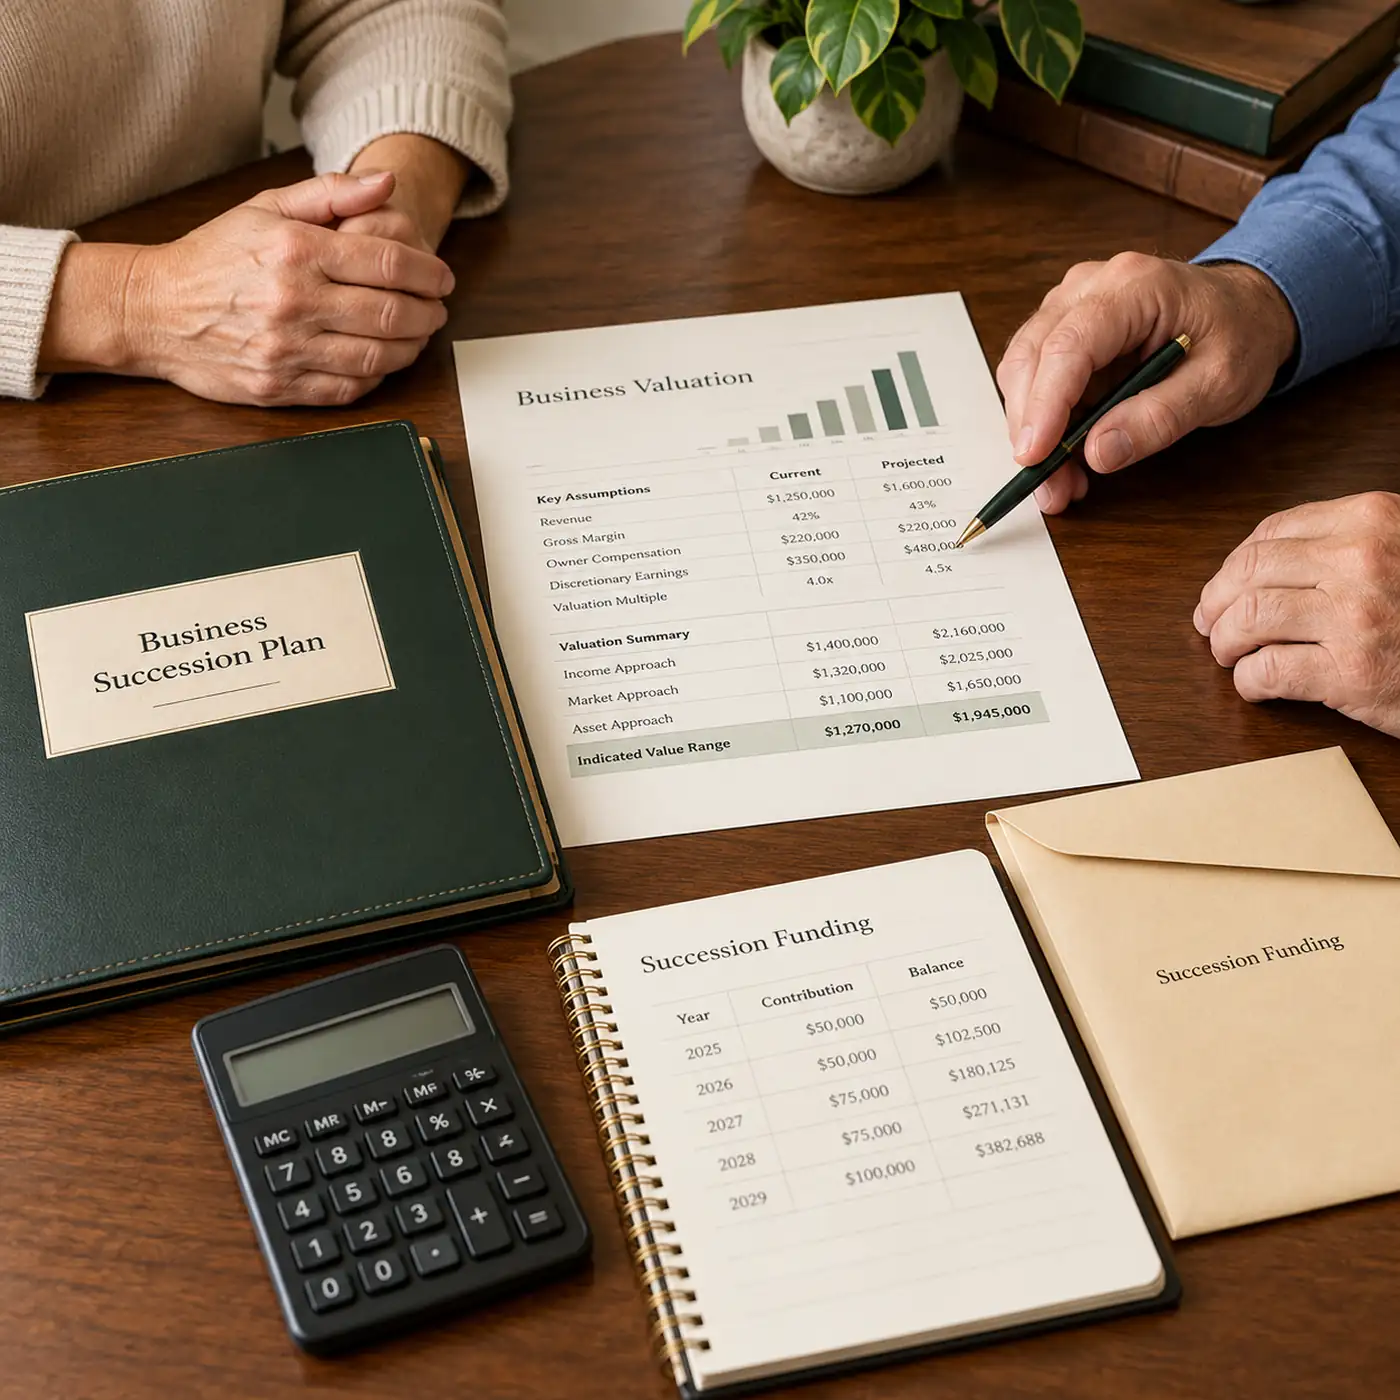
The agreement should say how the price is determined — a fixed price updated regularly, a formula or an independent appraisal at the time of the event — and how it is paid, whether in a lump sum funded by insurance or in installments. An unrealistic or outdated price is a common source of disputes, and a price that does not reflect fair market value can create estate tax problems.