
Review the estate route
Establish ownership and available alternatives.
Oakland · CA · Probate
A long-held home can raise probate and tax questions at the same time. Review the California estate transfer while keeping property tax assessment and inherited income tax basis separate.
California legal services · Office in Truckee, California
The family may know the old purchase price or property tax bill but not the current transfer route. Probate, property tax reassessment, and basis for a future sale address different issues. The Andrews Law Firm can discuss California probate from Truckee. Ask about availability for your matter and coordination with the appropriate tax adviser.
California legal guidance tailored to your needs
Establish ownership and available alternatives.
Distinguish assessment from income tax basis.
Connect transaction authority with estate obligations.
Collect the deed, will, trust documents, beneficiary records, and information about other estate assets. Establish the deceased person’s interest and whether alternatives to formal probate apply. The fact that a property was held for many years does not create automatic exemption from probate. Likewise, absence of a trust does not answer every transfer question. The §13151 petition ceiling for a qualifying California primary residence is $750,000 for deaths on or after April 1, 2025; it is not an automatic transfer right or a rule covering every property type. A supported ownership analysis should come before a filing, a sale commitment, or a promise about what each heir will receive.

For an appropriate local probate, the court is the Superior Court of California, County of Alameda. The person proposed to administer the estate needs the required authority before acting. Nomination in a will, family consensus, or possession of documents should not be treated as unlimited transaction power. Review any filings already made and required notices. Identify immediate property obligations, including insurance, financing, occupancy, and upkeep, so the home is not overlooked while the case is organized.
Acquisition documents, improvement records, ownership history, and valuations may be relevant to tax analysis even when the family expects a basis adjustment. Keep them rather than discard the old file after obtaining a current sale estimate. Tell the tax adviser about gifts, prior transfers, or co-owners that could affect the facts. The probate representative should coordinate the transaction and estate record without calculating a tax result from a general example. A step-up discussion is not a substitute for reviewing the actual ownership and applicable rules. Accurate records make it easier for the appropriate professionals to assess both the transfer and later sale questions.
A low property tax assessment and a low original purchase price are not interchangeable tax facts. An inherited asset may receive an income tax basis adjustment under applicable rules, while Proposition 19 raises separate property tax questions. For eligible family-home transfers during February 16, 2025–February 15, 2027, the adjusted valuation allowance is $1,044,586 above the existing taxable value. Continued eligibility depends on the family-home requirements, including the recipient’s qualifying principal-residence use and timely filing. Obtain appropriate valuation and tax advice based on the ownership and transfer. Do not assume a step-up preserves the old assessment or that probate itself guarantees a particular tax result. Preserve acquisition, improvement, and date-of-death valuation records for the professionals reviewing those issues.
If a sale is proposed, review the representative’s authority, applicable procedure, title requirements, and estate obligations. Statutory compensation: the ordinary-services schedule under Probate Code §§10800 and 10810. Property expenses and transaction costs may be separate. Sale proceeds should remain identifiable as estate funds until the applicable obligations and distribution requirements are addressed. Ask for an estate-specific sequence rather than a fixed promise of completion. Notices, inventory, tax coordination, accounting, disputes, and court scheduling can all affect the work after a buyer has been found.
 California estate planning counsel
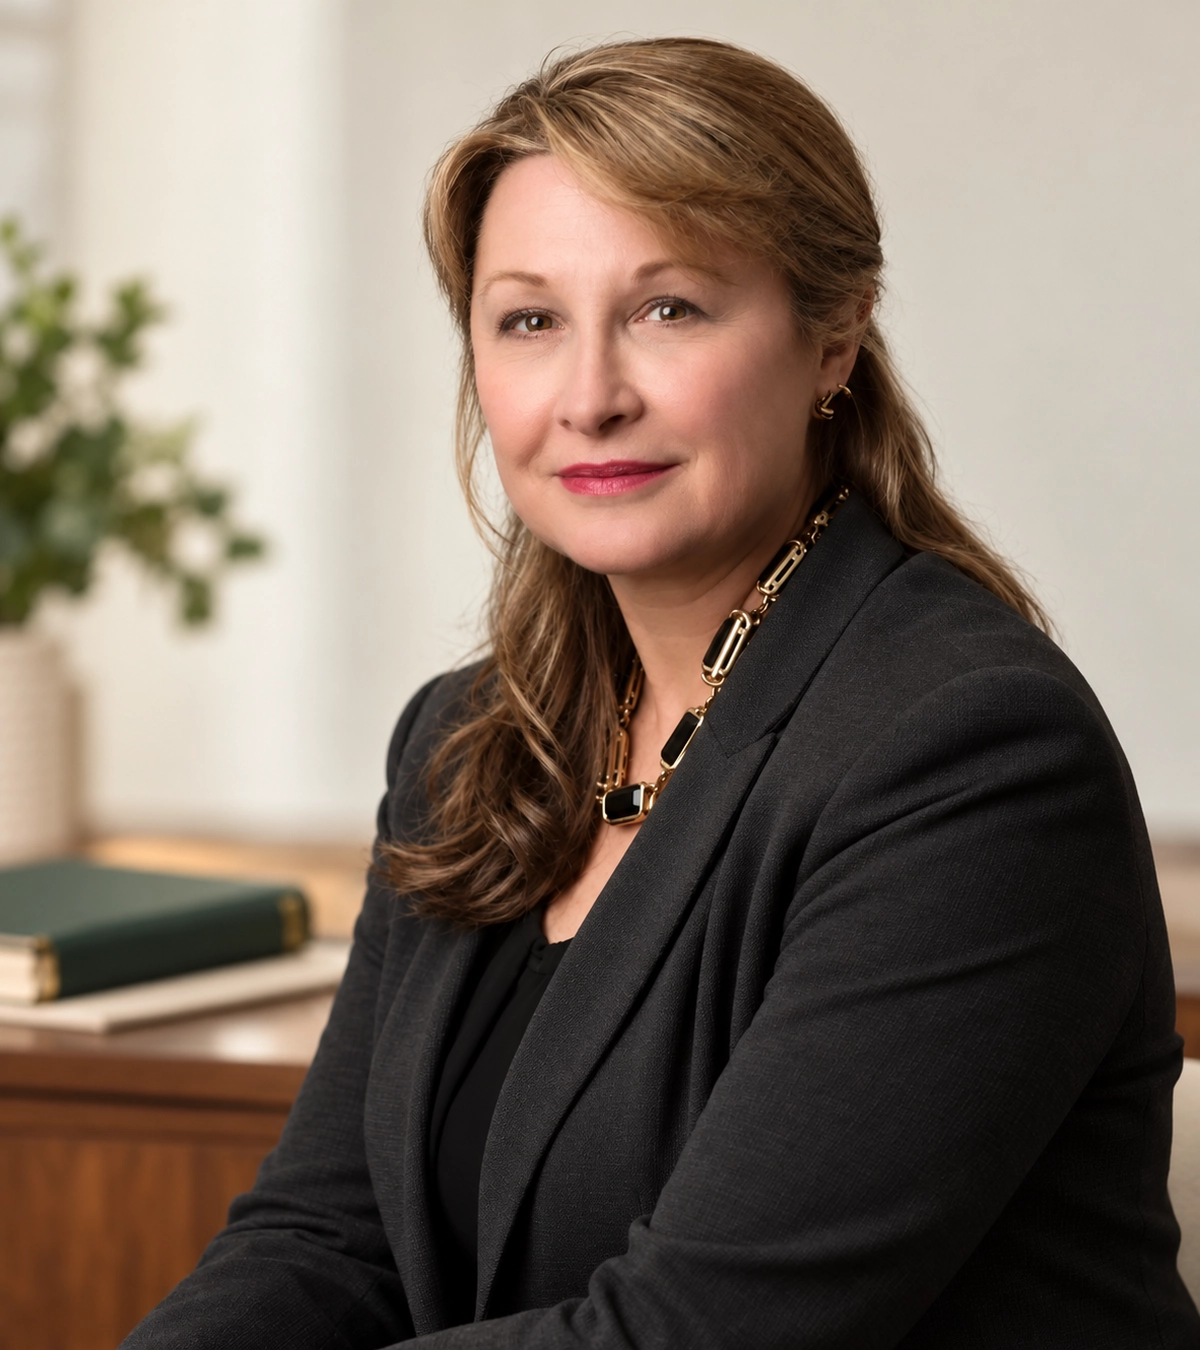
Meet your attorney · The Andrews Law Firm, P.C.
The family deserves a transfer plan and a clear list of tax questions for the right adviser.
Elaine Andrews can discuss California probate from the Truckee office. Confirm availability and proposed scope.
Tell the firm if a buyer, tax deadline, or court matter already needs attention.
Talk with ElainePrepare the decisions that need attention
Alameda County probate and property tax analysis should be coordinated without treating them as the same process.
Bring deeds, estate documents, death information, acquisition and improvement records, and any valuations or filings.
Identify the tax professional who will review basis and property tax questions.
Discuss the probate processCall (530) 550-8736 to talk about your California legal needs.
Estate administration
| Statutory fee base | Personal representative | Attorney | Combined |
|---|---|---|---|
| $1,000,000 | $23,000 | $23,000 | $46,000 |
Probate Code §§10800 and 10810 use 4% of the first $100,000, 3% of the next $100,000, and 2% of the next $800,000. The example assumes both full ordinary awards are approved. The statutory base is not reduced by mortgages. Court expenses and any extraordinary compensation are separate; this is not a fee quote.
California rules that apply in Alameda County
The relevant county is Alameda County. Confirm the procedure that fits the documents and assets.
Read the full probate guideIdentify the property and applicable venue.
Later amendments and ownership changes may matter.
The estate, residence, property location, and requested relief determine the appropriate court procedure.
This testimonial or endorsement does not constitute a guarantee, warranty, or prediction regarding the outcome of your legal matter.
Frequently asked questions
Our Truckee office
10270 Donner Pass Road
Truckee, CA 96161
Contact the Truckee office about consultation arrangements and whether the firm can assist with your matter.
Request a consultationBring your questions, your documents and the decisions you want help with. The first consultation is free.
This page provides general information, not legal advice. Contacting us does not create an attorney-client relationship.


