
Build the inventory
Separate trust property from other transfer routes.
Palo Alto · CA · Trust Administration
After a death, valuation work and tax questions can arrive before the successor has a clear inventory. Organize California trustee authority, appraisals, filings, and beneficiary duties from the beginning.
California legal services · Office in Truckee, California
A valuable home may be accompanied by investments, business interests, and records held by several advisers. The Andrews Law Firm can discuss California trust administration from Truckee, subject to availability. Estate and income tax work should be coordinated with the relevant tax professionals rather than assumed to follow one universal deadline.
California legal guidance tailored to your needs
Separate trust property from other transfer routes.
Match the evidence to its purpose.
Review returns, notices, and distribution needs.
Read the complete trust and amendments, establish who may act, and identify property actually held by the trust. Collect deeds, account statements, entity records, and information about assets passing through other routes. The trustee should not assume authority over every asset associated with the deceased. Probate Code §16061.7 notification requirements may apply and need review alongside ordinary administration communications. Record the triggering event, known contacts, and missing information so urgent tasks are identified without treating an incomplete inventory as the final estate picture.

A current asset list may not capture prior taxable gifts or earlier estate filings relevant to the federal review. Ask family members and advisers for the actual records, and identify missing information rather than entering an unsupported zero. The tax professional should assess filing and portability questions using the appropriate facts and current law. The trustee’s role is to organize and coordinate the record within the engagement, not to conclude from the home’s value alone that no return matters. Keep requests, responses, and reviewed deadlines documented so the administration can distinguish a resolved tax question from an assumption made before the necessary information was available.
Date-of-death values, current sale estimates, and valuations of business interests may serve different legal and tax needs. Ask which professionals and records are appropriate for each asset. A broker’s suggested listing price is not automatically a substitute for every required appraisal. Retain supporting materials and explain assumptions to the relevant advisers. If assets are discovered later, update the inventory and analysis. Valuation work should support accounting, tax coordination, and transfer decisions rather than exist as a single number copied across unrelated forms.
A trust may have income tax responsibilities, and an estate tax return or portability election may require attention depending on the circumstances. The 2026 federal basic exclusion is $15,000,000 for U.S.-citizen or U.S.-domiciled estates, with prior taxable gifts relevant to the calculation. Filing dates, extensions, and any available relief require individual review. Do not assume a return is unnecessary solely because the family expects no tax. Provide prior gift and estate returns to the tax professional. The trustee’s legal work and the preparer’s filing responsibilities should be clearly allocated, with a calendar based on the actual event and records.
Identify expenses, potential liabilities, property needs, and the information required to complete the administration. A substantial appraised value may coexist with limited cash. Review proposed sales, in-kind distributions, or advances within the trust’s authority and duties. Beneficiaries should receive appropriate information without a promise that everything can be paid out immediately. Keep accounts of receipts, expenses, valuations, transactions, and distributions separate from personal funds. The final record should show how legal, tax, and property decisions were coordinated and why assets or reserves were retained before final transfers.
 California estate planning counsel
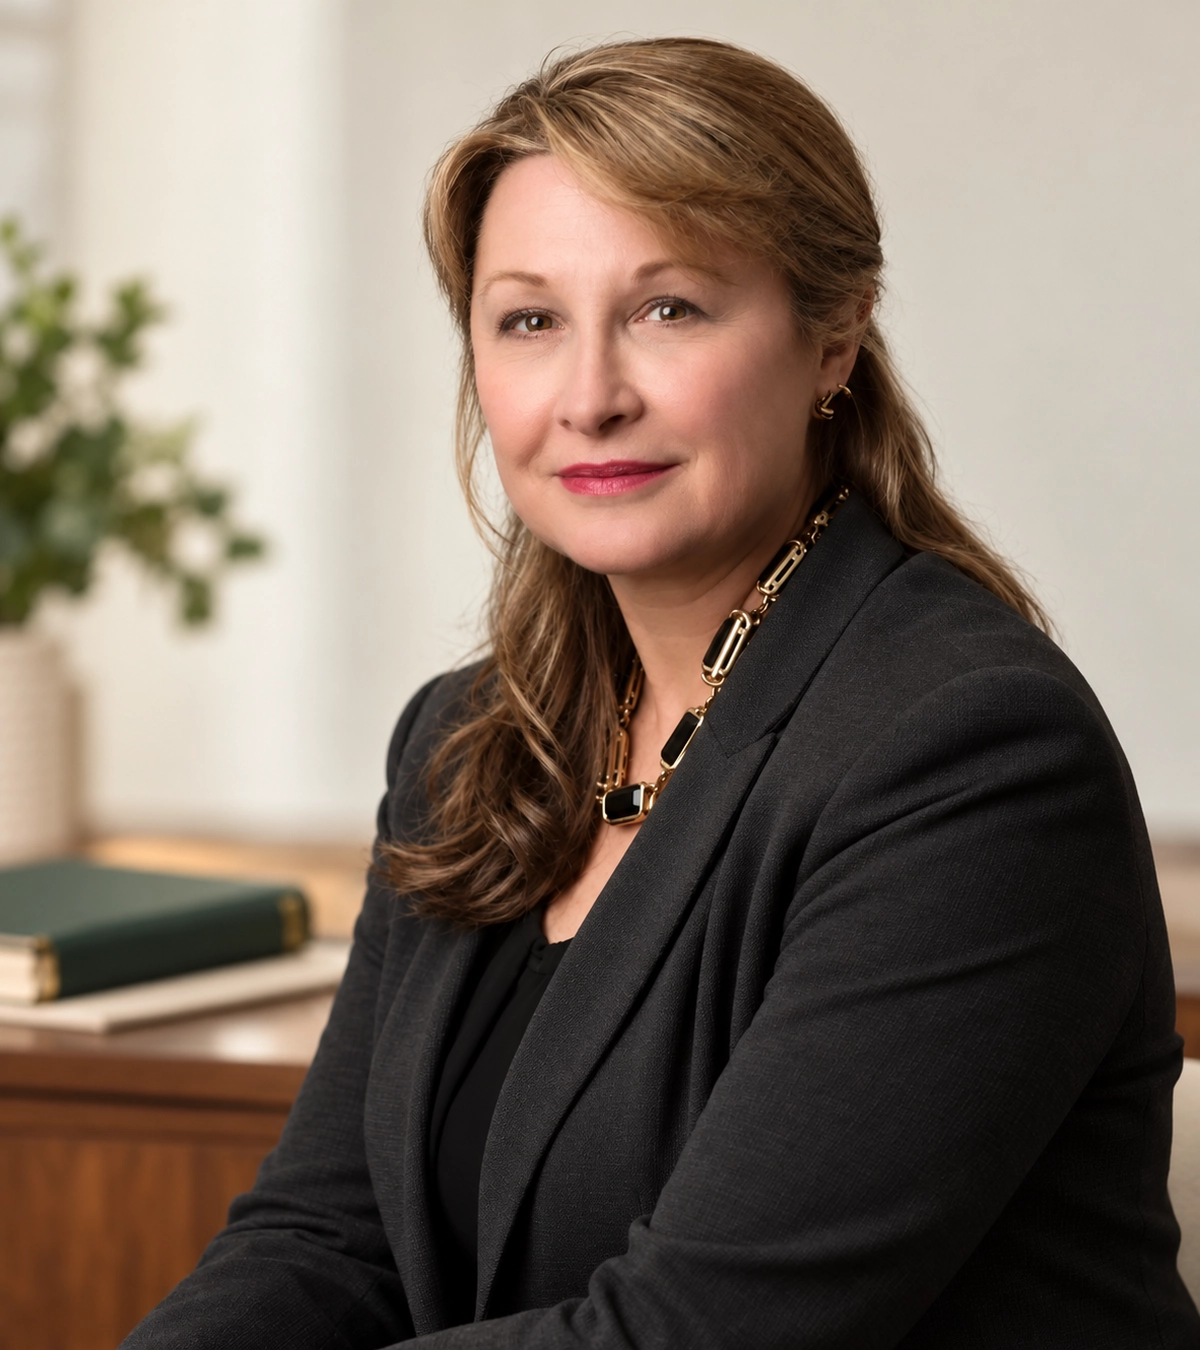
Meet your attorney · The Andrews Law Firm, P.C.
The successor needs a coordinated work plan rather than a collection of disconnected deadlines.
Elaine Andrews can discuss California trustee responsibilities from Truckee. Confirm availability for the proposed engagement.
Identify the tax preparer and advisers holding important records.
Talk with ElainePrepare the decisions that need attention
The Santa Clara County property is part of the inventory; tax and accounting needs may extend to assets held elsewhere.
Bring the trust, deeds, statements, valuations, prior tax filings, notices, and known deadlines.
Flag incomplete gift history or an estate return question early.
Get help with trustee dutiesCall (530) 550-8736 to talk about your California legal needs.
Trustee workflow
Confirm who may act under the trust.
Review Probate Code §16061.7 when applicable.
Document values, expenses, and decisions.
Communicate before final distribution.
California rules that apply in Santa Clara County
The relevant county is Santa Clara County. Confirm the procedure that fits the documents and assets.
Read the full trust administration guideIdentify the property and applicable venue.
Later amendments and ownership changes may matter.
Separate trust property from other transfer routes.
This testimonial or endorsement does not constitute a guarantee, warranty, or prediction regarding the outcome of your legal matter.
Frequently asked questions
Our Truckee office
10270 Donner Pass Road
Truckee, CA 96161
Contact the Truckee office about consultation arrangements and whether the firm can assist with your matter.
Request a consultationBring your questions, your documents and the decisions you want help with. The first consultation is free.
This page provides general information, not legal advice. Contacting us does not create an attorney-client relationship.


